
No, Aflac does not cover maternity leave itself. Aflac sells extra insurance, and some of its short-term disability plans can pay you cash while you recover from childbirth. The time off and job protection come from a separate federal law, the Family and Medical Leave Act, not from Aflac.
That mix-up trips up a lot of expecting parents. Whether Aflac pays anything for your pregnancy depends on your sign-up date and your plan. It also depends on whether your claim clears the waiting period before your due date.
🍼 What Aflac's maternity-related plans pay for
📅 Why sign-up timing can make or break your claim
⚖️ How Aflac differs from FMLA and state leave programs
💵 A worked example with real dollar numbers
✅ The mistakes that cost new parents their benefit
What Aflac Sells (and What It Isn't)
Aflac is a supplemental insurance company. It is not a government leave program, and it is not your main health plan. Companies offer Aflac policies as voluntary add-ons that workers pay for out of each paycheck. You choose whether to sign up, and you choose how much coverage to buy.
These policies do not grant time off on their own. They pay cash once you already qualify for leave under some other rule. That rule might be your company's own policy, a state law, or the federal Family and Medical Leave Act. The leave rule and the cash payout are two separate pieces of the same puzzle.
For pregnancy, the Aflac product that matters most is short-term disability. Aflac's own guidance treats a normal birth and its recovery as a covered event, much like a broken leg or surgery. You are not sick in the everyday sense. You simply cannot do your job for a set recovery window, and that gap is what the policy is built around.
The benefit is never automatic. You must have signed up early, cleared the waiting period, and sent in your doctor's paperwork on time. A plan bought after conception, or too close to your due date, may pay nothing at all, no matter how many premiums you have already paid. That one detail, timing, causes more denied claims than anything else in this guide.
Many companies pair short-term disability with a hospital indemnity plan, another Aflac product that pays a flat cash amount for a hospital stay. A birth that needs an overnight admission can trigger this second payout too. It replaces lost wages while you heal, while hospital indemnity offsets the copays and other costs a hospital birth brings. Signing up for both spreads the cost of a birth across two separate checks instead of one.
The Legal Leave vs. the Cash Benefit
Two different systems answer two different questions, and mixing them up is the biggest source of confusion here. One system decides whether your job is safe and whether your company must adjust your duties. The other decides whether any money shows up while you are out. Aflac only plays a role in the second one.
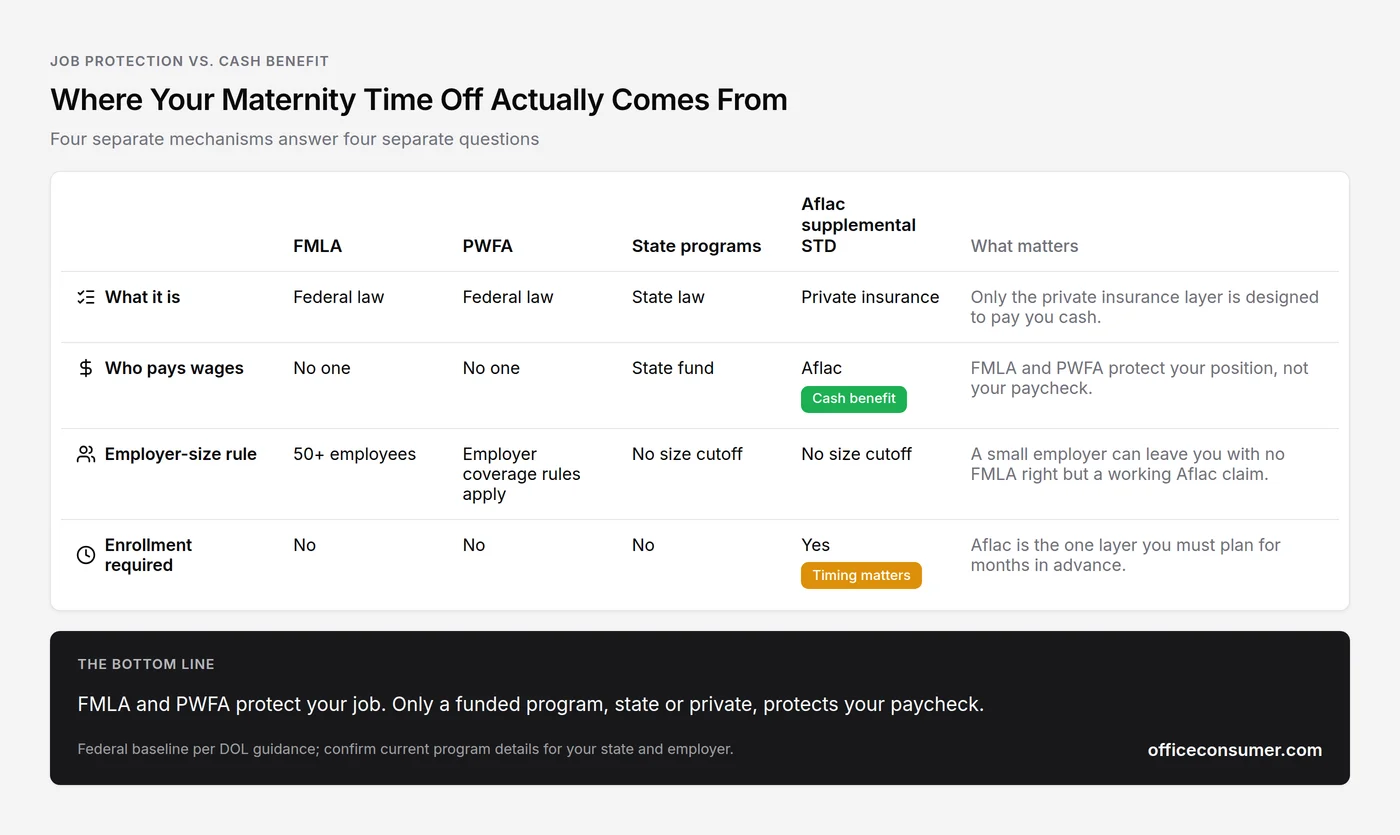
Federal law supplies the job-protection piece. The FMLA gives eligible workers at covered companies unpaid, job-protected leave for a birth or an adoption, per Department of Labor guidance. It also covers bonding time in the first year after the birth. The Pregnant Workers Fairness Act adds a second layer on top of that.
It requires covered companies to give reasonable accommodations for pregnancy, childbirth, and related health needs, unless doing so causes real hardship. Title VII bans firing, demoting, or otherwise punishing a worker for being pregnant. None of these three laws pays wages, and FMLA leave stays unpaid unless your company or a state program adds pay on top.
That gap, unpaid job protection with zero income behind it, is exactly what Aflac's disability plan is built to fill. It does not replace FMLA. It sits inside the window FMLA or a state law opens for you, and it puts money in your account while you are out. If your company is too small for FMLA, or you haven't worked there long enough, Aflac can still pay once your policy clears its waiting period.
Does your state differ? The federal rules above are the floor, not the ceiling. Several states run their own short-term disability or paid-family-leave programs, and those can pay wage replacement with no private insurance purchase at all. A state program often runs alongside your Aflac benefit rather than replacing it, so check your state's current rules before assuming Aflac is your only income source.
Which Situation Applies to You?
The answer changes sharply based on your timing, your company's size, and your state. Match your situation below before you assume anything about your benefit. Five common cases cover most workers, so find the one that fits you first.
You signed up before you got pregnant
This is the clean case. If your Aflac plan was active and past its waiting period before conception, most plans treat childbirth like any other covered event. You file a claim once your leave starts, send in your doctor's paperwork, and the plan pays its stated benefit for the covered recovery window. Confirm your exact waiting period on your certificate of coverage, since it can vary by plan and by state.
Most workers in this group face few surprises. The insurer already has months of active coverage on file before any claim begins. Keep a copy of your enrollment confirmation and your first premium statement, since a claims examiner may ask for proof the policy was active before conception. Once your doctor sends in the standard birth paperwork, a clean enrollment history is often the fastest path to approval.
You signed up after you were already pregnant
This is where claims get denied. Many insurance plans, Aflac's included, treat pregnancy like a pre-existing condition if it started before your coverage's effective date. Some plans also set a waiting window before a pregnancy claim can be paid. This mix-up catches many first-time parents off guard, and it is easy to avoid once you know the rule.
One returning policyholder found that Aflac had changed wording slightly. The plan began covering babies conceived during the paid coverage period instead of requiring a fixed birth-month cutoff. Ask your agent or HR contact for your plan's exact rule before you count on a payout, since the wording has reportedly shifted over time. A quick call now can save you a denied claim later, and it costs nothing to make.
You work for a small company
FMLA only covers companies with 50 or more workers within a 75-mile radius. Because of that line, a large share of small-business workers have no federal job-protection right at all. Aflac's cash benefit does not depend on company size. If you signed up and your waiting period has passed, the insurance pays whether or not FMLA applies to your job.
Job protection and income replacement are not the same guarantee, and a small-company worker often has the second without the first. That split matters most when a company cannot legally promise your role back but can still pay your Aflac claim in full. Plan your budget around the benefit you can prove, not the protection you assume you have. Ask your HR contact directly whether your company falls under the federal threshold, since many small-business workers never find out until they need the leave.
You are having a C-section or a complicated birth
Complications extend the covered recovery window and change your math. A vaginal birth often means a shorter leave than a surgical birth, and diagnosed complications like preterm labor can stretch it further. A single extra week of documented recovery can add real dollars to your total payout. Ask your doctor to log any complication right away, since Aflac pays based on what your paperwork shows, not the calendar you first expected.
Some workers who hit complications before their coverage matured contacted Aflac about the protocol its medical team follows for an early preterm labor. Get your doctor's paperwork updated the moment your recovery timeline changes. Your claim pays based on documented medical need, not a fixed calendar guess. A short note from your doctor now can prevent a fight over your payout later.
You're self-employed or work gig jobs
FMLA and most company-sponsored Aflac plans assume a traditional employer-employee setup, so freelancers, contractors, and gig workers usually cannot reach either one through a workplace. Aflac does sell individual policies straight to people with no employer plan behind them, and self-employed workers can buy this coverage on their own. Rideshare drivers, freelance designers, and other independent workers fall into this same coverage gap far more often than salaried staff.
That coverage follows the same waiting-period rules described above. There is no company safety net behind a gig worker's income, so buying a policy early matters even more here. It matters more than it does for a traditional worker with other backstops in place. Waiting until you are pregnant to shop for a policy is the single costliest mistake in this situation.
How the Aflac Maternity Benefit Works
Three variables decide what lands in your bank account: the waiting period, the benefit percentage, and the covered duration. Get any one of them wrong in your planning, and the payout will surprise you. Each one is worth understanding on its own.
The waiting period, sometimes called an elimination period, is the stretch of time your plan must be active before a pregnancy claim qualifies. Aflac's own materials describe plans that will not approve claims filed within roughly the first several months of coverage. A plan bought after conception often misses its own window entirely. Treat this as a plan you buy before you conceive, not one you shop for once you're already expecting.
The benefit percentage is not 100% of your pay. According to Aflac's guidance, approved claims often replace between 40% and 70% of your income. The exact share depends on the coverage level you picked at enrollment. Aflac plans often let you choose a flat monthly amount instead of a fixed percentage.
The covered duration depends on your birth type and any documented complications. One law firm's overview of insurance plans describes many plans covering six to eight weeks for a vaginal birth, and up to twelve weeks for a C-section. That is a general pattern from one source, not a promise. Your own certificate of coverage governs your specific claim.
Worked Example: Calculating a Realistic Payout
Mara earns $4,000 a month before taxes as a marketing coordinator. She enrolled in an Aflac plan eight months before she got pregnant, clearing the plan's waiting period well ahead of conception. At enrollment, she picked a coverage level built to replace about 60% of her income, landing her a monthly benefit of $2,400.
Mara delivers by C-section, and her doctor certifies a ten-week recovery period. Over that stretch, Aflac pays her $2,400 a month, or about $554 a week, for roughly ten weeks. That totals close to $5,540 in extra income during a stretch when her regular paycheck stops, since FMLA leave alone is unpaid.
Now compare Mara to a coworker who signed up the same month she found out she was pregnant. That coworker's claim likely falls inside the plan's waiting period. By the time the waiting period clears, her leave may already be over, leaving her with nothing from the plan.

Lessons From How the Coverage Plays Out in Real Companies
Three separate situations show how the same policy can produce very different outcomes. The details most workers overlook are the ones that end up costing them the most. Each one points to a specific fix you can make before you ever file a claim.
The benefit stack that nearly replaced her full paycheck
Priya, a warehouse supervisor, lives in a state that runs its own short-term disability program funded through payroll tax. She also carried a private Aflac plan through her employer, bought well before she got pregnant. When she went on leave for a C-section, both programs paid out at the same time, since one did not cancel out the other.
The state program covered a share of her wages on its own schedule, and her private Aflac benefit paid its separate monthly amount on top. Combined, the two payouts landed closer to her full paycheck than either program could reach alone. Priya had no idea the two could stack until her HR contact mentioned it during open enrollment. The lesson is not that stacking is automatic, but that a private plan and a state program are not mutually exclusive, and checking both is often what gets a worker closest to full income replacement during leave.
| Benefit source | What it adds |
|---|---|
| State disability program | Wage replacement set by state law, where a program exists |
| Private Aflac plan | A separate cash amount, based on the coverage level you chose |
| Both combined | Closer to full income replacement, though rarely a full 100% |
The small-company worker with no FMLA safety net
Devon worked at an 18-person marketing agency, well under the 50-worker FMLA line. His company had no federal duty to hold his job during his partner's recovery or his own time off. His company did offer voluntary Aflac coverage, and because Devon signed up a year earlier, his claim paid out during the four weeks he took off to help at home. His HR contact never mentioned that FMLA simply did not apply to a company that size.
He had income without job protection, the mirror image of a large-company worker who often has protection without automatic income. That gap matters, since assuming "my company offers Aflac, so I'm covered like FMLA" is a common and costly misread. The two benefits answer different questions, and only one of them puts cash in your pocket.
The complication that changed the claim mid-stream
Janelle went into preterm labor at 32 weeks, well before her planned leave date, and her first paperwork covered only a standard six-week recovery. Her doctor filed updated paperwork citing the complication, and her claim stretched to eleven weeks of benefit at the same monthly rate. Nothing about her original enrollment or waiting period changed.
What changed was the documented medical need, and that need is the real lever behind an approved claim's length. It is not a fixed "maternity leave" calendar. A worker who updates her paperwork the moment her situation changes protects her full benefit. One who does not risks leaving weeks of pay on the table.
| Delivery scenario | General pattern seen in policy commentary |
|---|---|
| Uncomplicated vaginal birth | Shorter window, often cited around 6 to 8 weeks |
| C-section without complications | Longer window, often cited up to about 12 weeks |
| Documented complications, either birth type | Extended per doctor's updated certification |
Mistakes to Avoid
- Buying coverage after conception and assuming it will pay. Most plans set a waiting period from the policy's start date, and a late sign-up routinely lands inside that window, so the claim gets denied.
- Confusing Aflac with paid family leave. Aflac is private, supplemental insurance you choose and pay for. Skipping enrollment means skipping the benefit entirely, with no automatic backup.
- Assuming FMLA guarantees pay. FMLA guarantees unpaid, job-protected time for eligible workers at covered companies. Without a disability plan, state program, or paid company leave on top, FMLA alone puts zero dollars in your account.
- Not updating your doctor's certification after a complication. A claim filed for a standard vaginal birth will not automatically stretch for a C-section or preterm labor unless your doctor sends updated paperwork.
- Missing your company's enrollment window. Voluntary benefits like Aflac usually open during a set yearly window or a qualifying life event, and missing it can mean waiting a full year to sign up.
- Assuming the benefit replaces your full salary. Aflac's own guidance describes typical payouts landing between 40% and 70% of income, so budgeting for full wage replacement sets up a real shortfall.
- Skipping the "does my state differ" question. Several states run their own disability or paid-leave programs that can pay alongside a private plan, and ignoring that layer can leave real money unclaimed.
- Firing or sidelining a worker soon after they return from leave. Workers who discuss this online warn that letting someone go too soon after a leave return can draw lawyers ready to make a costly retaliation case out of it.
- Filing a claim with no proof of your enrollment date. Claims examiners check both your start date and your waiting-period completion, and a worker who cannot document either one often waits far longer for a decision.
Do's and Don'ts for Aflac Maternity Coverage
Do
- Sign up well before you plan to conceive, since most waiting periods run several months and a late start can void the benefit entirely.
- Read your certificate of coverage for the exact waiting period, because it varies by state and by the specific plan your company offers.
- Ask HR whether your state also runs a mandatory disability or paid-leave program, since a state benefit can run alongside your Aflac payout.
- Keep your doctor's certification current, especially if your recovery timeline changes because of a complication or a C-section.
- Confirm whether your benefit is a flat dollar amount or a share of pay, so your budget for the leave period reflects reality, not a guess.
- Save proof of your enrollment date, since a clean paper trail is what moves a claim through review the fastest.
Don't
- Don't wait until you are pregnant to enroll, since a late sign-up routinely lands your claim inside the plan's own waiting period.
- Don't assume Aflac and FMLA are the same protection, since one pays cash and the other only protects your job, not your paycheck.
- Don't assume every company offers the same Aflac plan design, since benefit levels, waiting periods, and covered durations are set separately by each employer.
- Don't skip your state's disability program research, since some states legally require employer-provided coverage that can add income on top of a private plan.
- Don't submit a claim with no medical certification attached, since incomplete paperwork is one of the most common reasons a payout gets delayed.
- Don't treat the benefit percentage as guaranteed income, since it is tied to the coverage level you picked, not to your full salary automatically.
Pros and Cons of Relying on Aflac During Maternity Leave
Pros
- Pays regardless of company size, unlike FMLA, which only covers companies above the 50-worker threshold.
- Fills the unpaid gap FMLA leaves open, giving workers real income during time off that federal law does not cover.
- Coverage level is chosen by the worker, so someone who wants a bigger benefit can often pick a richer plan tier at enrollment.
- Claims often move faster than a public benefits program, since a private insurer runs the review instead of a state agency queue.
- Payroll deduction makes it simple for a company to offer, without having to design its own paid-leave policy from scratch.
Cons
- Waiting periods make it useless for a claim you did not plan ahead of time, which surprises workers who enroll only after learning they are expecting.
- The payout is partial, not a full salary, often landing between 40% and 70% of income according to Aflac's own guidance.
- Coverage depends entirely on your company choosing to offer it, so workers at companies with no voluntary benefits program have no access at all.
- Premiums come out of your paycheck, so the benefit is not free money. You pay for it over months or years before you ever file a claim.
- It provides no job protection on its own, so a worker at a small or non-covered company could still lose their role even while the Aflac payout continues.
What to Do Next
- Pull your Aflac certificate of coverage and find the exact waiting period for a pregnancy-related claim.
- Compare your policy's effective date to your conception date to see whether your claim will clear the waiting period before birth.
- Check whether your state runs a mandatory short-term disability or paid-family-leave program that could add income on top of your Aflac benefit.
- Ask HR whether your company meets the 50-worker FMLA threshold, since that decides your job-protection rights separately from your Aflac payout.
- Have your doctor prepare documentation now, and update it right away if your recovery timeline changes because of a complication.
- If your situation is complicated, talk to HR, an employment attorney, or a benefits counselor before you assume any specific dollar figure or duration applies to you.
Frequently Asked Questions
Does Aflac cover maternity leave itself?
No. Aflac does not grant leave or job protection on its own. Its disability plans can pay a cash benefit during a covered pregnancy-related recovery. The leave and job protection themselves come from FMLA, state law, or your company's own policy.
How much does Aflac pay for a maternity claim?
It depends on your selected coverage level. According to Aflac's own guidance, approved claims often replace between 40% and 70% of your income, based on the benefit amount you chose at enrollment.
Is there a waiting period before Aflac pays a pregnancy claim?
Yes. Many Aflac plans set a waiting period measured from the policy's effective date. A claim filed inside that window is commonly denied, so enrolling well before conception matters.
Does Aflac cover C-sections differently than vaginal birth?
Yes, in practice. Recovery windows for a C-section commonly run longer than for an uncomplicated vaginal birth. Duration follows the medical paperwork your doctor files, not one fixed number for every plan.
Can I enroll in Aflac after I'm already pregnant?
You can enroll, but your claim may not pay. Late enrollment often means your pregnancy falls inside the plan's waiting period. The claim can then be denied even though you technically hold coverage by the day you give birth.
Does an Aflac maternity benefit count as FMLA leave?
No. FMLA is a separate federal job-protection law with its own qualifying rules, including a 50-worker threshold for covered companies. Getting an Aflac payout does not automatically make your time off FMLA leave, and the reverse is also true.
Is the Aflac maternity benefit taxable?
It depends on how your premiums were paid. Disability benefits funded with post-tax payroll deductions are often received free of income tax. Employer-paid premiums can change that outcome, so confirm the tax treatment with your plan documents or a tax professional.
What happens if my company doesn't offer Aflac?
You have no access to that specific benefit. Aflac coverage is entirely company-sponsored and voluntary. Workers whose employer skips it must rely on FMLA job protection, a state disability program, or personal savings instead.
Does Aflac cover pregnancy complications like preterm labor?
Often yes, with updated paperwork. A claim first certified for a standard birth can extend once your doctor sends updated paperwork describing a complication. Covered duration follows documented medical need, not a fixed calendar.
How long does an Aflac maternity claim take to process?
It varies, but private insurers often move faster than public benefit programs. Processing speed depends on how quickly your doctor sends certification. It also depends on how clearly your enrollment date and waiting-period completion are documented.
Do I need FMLA approval to receive Aflac disability benefits?
No. Aflac's payout depends on your policy's own terms, not on whether you qualify for FMLA. A worker at a small company with no FMLA coverage can still get an Aflac payout, as long as the policy is active and past its waiting period.
Does Aflac offer a paternity leave benefit too?
Short-term disability is built around the birthing parent's own recovery, not general bonding time. A non-birthing parent often has no personal claim of their own. Some companies do pair Aflac with a separate paid parental leave policy for bonding time.